Change region
 United States
 United Kingdom
 Australia
 New Zealand
 South Africa
 Saudi Arabia
 United Arab Emirates
 Kuwait
 Qatar
 Nigeria
 Cyprus
Quick answer: For "cibc costco world mastercard": a store credit card or financing offer is a loan, so compare the interest rate, fees and terms in the written agreement, and use the Financial Consumer Agency of Canada's tools. We quote no rates or approval odds.
Last updated: October 2026. We quote no live prices; facts come from the sources listed and may have changed; worked numbers are invented.
Background
A search for "cibc costco world mastercard" often comes from someone wondering whether to take a retailer's credit card, a co-branded Mastercard or Visa, or a pay-later offer. Co-branded cards are issued by banks or financial institutions, not by the shop itself, and they earn rewards such as points or store credit. We do not know the current rates, fees or reward rules for any card, and they change, so we state none.
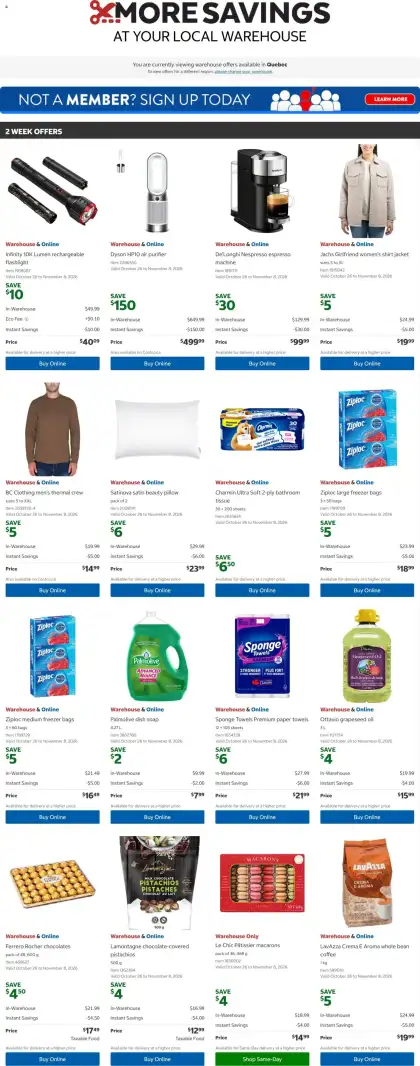
In Canada, the Financial Consumer Agency of Canada (FCAC) regulates federally regulated financial institutions' consumer practices and publishes plain-language comparison tools. Provincial laws regulate some store-issued credit and pay-later products. A purchase interest rate on credit cards is often a high annual percentage rate, and carrying a balance can cost far more than the rewards earn. If the Costco offers are not quite what you need, it is worth comparing them with the latest Walmart flyer and the current Canadian Tire flyer before you decide.
Interest-free or deferred-payment promotions may charge interest from the purchase date if the balance is not paid in full by the end date, and some require a minimum monthly payment that does not clear the balance in time. Read the agreement and the disclosure box before signing.
What to check and how to decide
Before you apply, compare the annual percentage rate on purchases and cash advances, the annual fee, the interest-free grace period, the foreign-transaction fee and how rewards are earned and redeemed. Each application may trigger a hard credit check, and several applications in a short time can lower your credit score. If you carry a balance, a low-rate card usually beats a high-reward card.
Financing and pay-later offers deserve the same scrutiny. Ask for the total cost in dollars, the number and dates of payments, late-payment fees and what happens if you return the item. Do not accept financing in a hurry at the till; take the written terms home and compare them with a bank loan or a line of credit.
Never share card numbers, one-time passcodes or your Social Insurance Number with someone who contacts you out of the blue. The Canadian Anti-Fraud Centre advises using the official app or website, and calling the number on the back of your card if you are unsure.
| Item | What it means |
|---|---|
| Annual interest rate | High on many cards; compare |
| Annual fee | Check against rewards |
| Promotional financing | Read what triggers interest |
| Credit check | Applications can lower your score |
Common mistakes with store cards and financing
A frequent mistake is accepting a card at the till for a one-off discount without reading the terms. Welcome discounts are usually small compared with the interest on a balance carried month to month. Another is misunderstanding promotional financing, where interest can be charged retroactively on the full original amount if the promotion is not fully paid in time.
Rewards can also mislead. Points are only valuable if you redeem them at a reasonable rate and do not overspend to earn them. Compare the real value of the rewards with the annual fee and the interest you would pay. Keep your credit utilisation low, because high balances can reduce your credit score.
- Read the terms before applying
- Pay the full balance on time
- Calculate the real value of rewards
- Avoid applying for many cards quickly
- Check statements for errors
- Know how to dispute a charge
Common mistakes to avoid
A common mistake is relying on a single source. Prices, ranges and policies at Costco Canada change often, and the same item may differ between stores, regions and online. Check the official site or app, compare with one competitor, and look at total cost, including fees and taxes. In Canada, shelf and flyer prices normally exclude GST or HST and, in some provinces, PST or QST, so the amount at the till is higher than the sticker.
Another mistake is skipping the paperwork. Keep receipts, order confirmations, warranty terms and serial numbers, and photograph large purchases on arrival. These records speed up returns and complaints. If you buy something that fails or is not as described, contact the seller first, in writing, and keep a copy.
A third is trusting unsolicited offers. Coupon links, "free gift card" messages and lookalike websites are common, and they often ask for personal or payment details. If a deal sounds too good to be true, go straight to the retailer's own site. If you need help with a dispute, provincial consumer-protection offices and the Competition Bureau Canada can explain your rights.
- Check the official site or app
- Compare total cost with one other seller
- Keep receipts and serial numbers
- Read return and warranty terms
- Ignore unsolicited coupon links
- Ask for help early if something goes wrong
A closer look at the category
Whatever you are buying, the same discipline applies: define what you need, compare at least two sellers on the total cost, check the return and warranty terms, and keep your proof of purchase.
Consumer tips and alternatives
Pay the full statement balance by the due date if you can, set up automatic payments for at least the minimum, and check your statements for unfamiliar charges. If you have a dispute with a merchant, contact the card issuer promptly.
Alternatives include a low-rate card, a savings plan, a line of credit or simply waiting for a sale. A store card makes sense only if you will pay it off every month and the rewards are worth more than the fee and the temptation to spend.
If you cannot keep up with payments, contact the lender early and consider free credit counselling through a non-profit credit-counselling agency. The FCAC publishes guidance, and you can request your credit report free from Canada's credit bureaus.
Check, compare and keep records. Those three habits protect you whichever store you are dealing with, and they cost nothing. Remember that Canadian shelf prices usually exclude GST or HST and provincial sales tax, so the till total is higher, and that in Quebec stores must offer French-language service and labelling.
Frequently asked questions
Is a store credit card a good idea?
Only if you pay the balance in full each month and the rewards beat the fees.
Who issues the card?
A bank or financial institution, not the shop; read the agreement.
Are rates shown here?
No; check the issuer's current disclosure.
Sources
- Costco Canada official website (costco.ca) - ads, store locator, loyalty and policy pages (consult the live page; this article does not reproduce current prices)
- Canadian Anti-Fraud Centre (antifraudcentre-centreantifraude.ca) - guidance on shopping scams and fake coupons
- Canadian Food Inspection Agency (inspection.canada.ca) - food-safety and refrigeration guidance
- Financial Consumer Agency of Canada (canada.ca/en/financial-consumer-agency) - credit card comparison tools and guidance
- Canadian Anti-Fraud Centre (antifraudcentre-centreantifraude.ca) - scam warnings, including fake coupons and job offers